5. What is the Significance of the Balance Sheet?
The Balance Sheet is one of the three main financial statements (along with the Profit & Loss Statement and Cash Flow Statement). It provides a snapshot of a company’s financial position at a specific point in time, typically at the end of a financial quarter or year.
Unlike the P&L Statement, which reflects performance over a period, the Balance Sheet shows what the company owns and owes on a particular date, and how those resources are financed—whether through debt or equity.
It is an essential tool for assessing a company’s liquidity, financial strength, risk exposure, and long-term sustainability.
Structure of the Balance Sheet
The Balance Sheet is structured around the fundamental accounting equation:
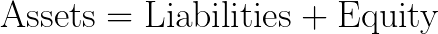
This equation must always balance, ensuring the company’s resources (assets) are fully accounted for by its obligations (liabilities) and ownership interest (equity).
1. Assets
Assets are economic resources controlled by the company that are expected to generate future benefits.
They are usually categorized into:
- Current Assets (short-term):
Includes cash, inventory, accounts receivable, short-term investments, etc. These are assets expected to be converted into cash or used up within one year.
- Non-Current Assets (long-term):
Includes property, plant, equipment, long-term investments, intangible assets (like patents, goodwill), etc. These provide value over a longer period.
2. Liabilities
Liabilities are the company’s financial obligations or debts owed to external parties.
They are categorized into:
- Current Liabilities:
Obligations that are due within one year such as accounts payable, short-term loans, salaries payable, taxes owed.
- Non-Current Liabilities:
Long-term debts and obligations like bonds payable, long-term loans, deferred tax liabilities, lease obligations, etc.
3. Equity (Shareholders’ Funds)
Equity represents the owners’ interest in the company after all liabilities are deducted from assets.
It includes:
- Share Capital
- Retained Earnings (profits reinvested in the business)
- Reserves and Surplus
Equity answers the question: *What portion of the business is financed by its owners?*
Sample Balance Sheet Format (₹ in Crores)
| Particulars | FY 2023 | FY 2022 |
|---|---|---|
| Assets | ||
| Current Assets | 10,000 | 8,500 |
| Non-Current Assets | 18,000 | 16,200 |
| Total Assets | 28,000 | 24,700 |
| Liabilities | ||
| Current Liabilities | 6,500 | 5,800 |
| Non-Current Liabilities | 7,000 | 6,200 |
| Total Liabilities | 13,500 | 12,000 |
| Equity | ||
| Shareholders' Equity | 14,500 | 12,700 |
| Total Liabilities + Equity | 28,000 | 24,700 |
What Can Investors Learn From the Balance Sheet?
- Liquidity:
Can the company pay its short-term obligations with its current assets? *(Measured using the Current Ratio or Quick Ratio)*
- Solvency:
Is the company over-leveraged or operating with a healthy capital structure? *(Measured using the Debt-to-Equity Ratio)*
- Asset Utilization:
How efficiently is the company using its assets to generate income?
- Financial Flexibility:
Does the company have the resources to invest in growth, handle downturns, or distribute dividends?
Key Takeaways
- The Balance Sheet reflects a company's financial standing at a point in time.
- It shows the resources (assets) the company controls, the obligations (liabilities) it owes, and the net ownership (equity) of its shareholders.
- It is critical for analyzing liquidity, leverage, and long-term financial health.
- Investors use it to evaluate whether a company is stable, solvent, and positioned for growth.